Consumer debt has climbed to new highs, and even with a slight cut in interest rates, paying it down has become more expensive. That makes now a good time to focus on getting out of debt — but it also means you need a smart approach. Carrying a large balance can feel daunting, yet a clear plan can make the process more manageable. Avoiding common missteps can help you stay motivated and make real progress.
Not Having a Plan
Before you start making extra payments, map out a strategy. Figure out how much you owe, which debt you want to tackle first, and how much you can realistically put toward payoff each month. If you’re unsure where to begin, a financial planner can be a helpful first step.
Spreading Extra Money Across Every Debt
If you send a little extra to every balance, progress can feel almost invisible — and that can make it harder to stay committed. A better approach is to focus extra payments on one debt while continuing to make the minimum on the others.
Picking the Wrong Payoff Method
The two most common strategies are the snowball and the avalanche. The snowball method targets the smallest balance first, regardless of interest rate, and then moves to the next debt after that one is eliminated. The avalanche method focuses first on the debt with the highest interest rate, then works downward.
The snowball method can be motivating because it delivers quick wins. The avalanche method is usually the most cost-effective choice, since paying off a credit card charging 22% interest makes more financial sense than tackling a car loan at 4% to 5%. The best method is the one you will actually stick with.
Avoiding Your Full Debt Picture
Debt can feel overwhelming enough that you may not want to look at your balances at all. But ignoring the numbers will not make them go away. If you want to stop the stress of overdue bills and mounting interest, you have to face the full picture.
Not Knowing Your “Why”
Long, difficult goals are easier to reach when you have a strong reason behind them. Before you begin, define your “why.” Maybe you want less stress, the freedom to leave a job you dislike, a financial cushion, or the ability to start a family. Knowing your motivation can help you stay on track when the process gets hard.
Trending on Cheapism
Refusing to Make Sacrifices
Once you understand your goal, it becomes easier to give up some things along the way. Cutting back on weekly nights out, a pricier car, or a larger apartment may not feel good, but without some sacrifices, paying off debt can be much harder.
Sacrificing Too Much
On the other hand, going too far can backfire. Some people try to pay off debt by living on rice and beans for years, but for most people that is not sustainable. If you give up everything that brings you joy, you may eventually quit. The goal is balance.
Setting Unrealistic Goals
Paying off all your debt in a short time would be ideal, but that timeline may not be realistic. Everyone’s financial situation is different, and your debt payoff plan should reflect your own circumstances. Success may take years, and that is still success if it is realistic for you.
Sign up for our newsletter
Subscribe to Cheapism and get exclusive tips, top deals, and money-saving ideas sent directly to you.
Keeping Your Income Flat
Not everyone can take on a side hustle, but increasing income can speed up debt payoff. If you can earn more at your current job or add another source of income, you’ll have more money available to throw at your balances while keeping spending steady or lower.
Skipping Accountability
Once your plan is in place, it helps to tell someone you trust. A friend, partner, or relative can serve as an accountability partner and keep you focused when motivation dips.
Forgetting to Apply Extra Payments to Principal
Sending more money to a lender is not enough on its own. You need to make sure the extra goes toward principal only, not just interest. That helps reduce the loan balance faster and cuts down on total interest paid. Just be sure your lender allows principal-only payments without fees or penalties.
Skipping an Emergency Fund
It can be tempting to direct every spare dollar toward becoming debt-free, but without an emergency fund, one unexpected expense can send you right back into debt. Before putting all extra money toward loans, build at least a small emergency cushion. Some experts suggest $1,000, while others recommend saving three to six months of living expenses.
Leaving Some Debt Out
Some obligations are easy to overlook, but they still need to be included in your payoff plan. That includes debt sent to collections and zero-percent-interest loans, especially because promotional rates often rise later. Leaving them out is a mistake.
Not Automating Payments
Automated debt payments can keep you consistent. They reduce the chance of forgetting a due date, and they make it less tempting to spend money that should go toward your balances. Automation also removes some of the emotional strain from the process.
Overlooking Refinancing or Consolidation
Refinancing or consolidating loans may lower your interest rate and make repayment simpler. It may also reduce your monthly payment and free up money for higher-interest debt. If you are considering student loan refinancing or consolidation, make sure you understand how it could affect repayment benefits, including forgiveness programs.
Ignoring Balance Transfers
High-interest debt can be especially hard to conquer. One option worth considering is a balance transfer, since some credit cards let you move debt to a lower rate — sometimes even 0% for a limited time. That can give you a window to pay down the balance before interest builds again.
Adding More Debt While Trying to Pay It Off
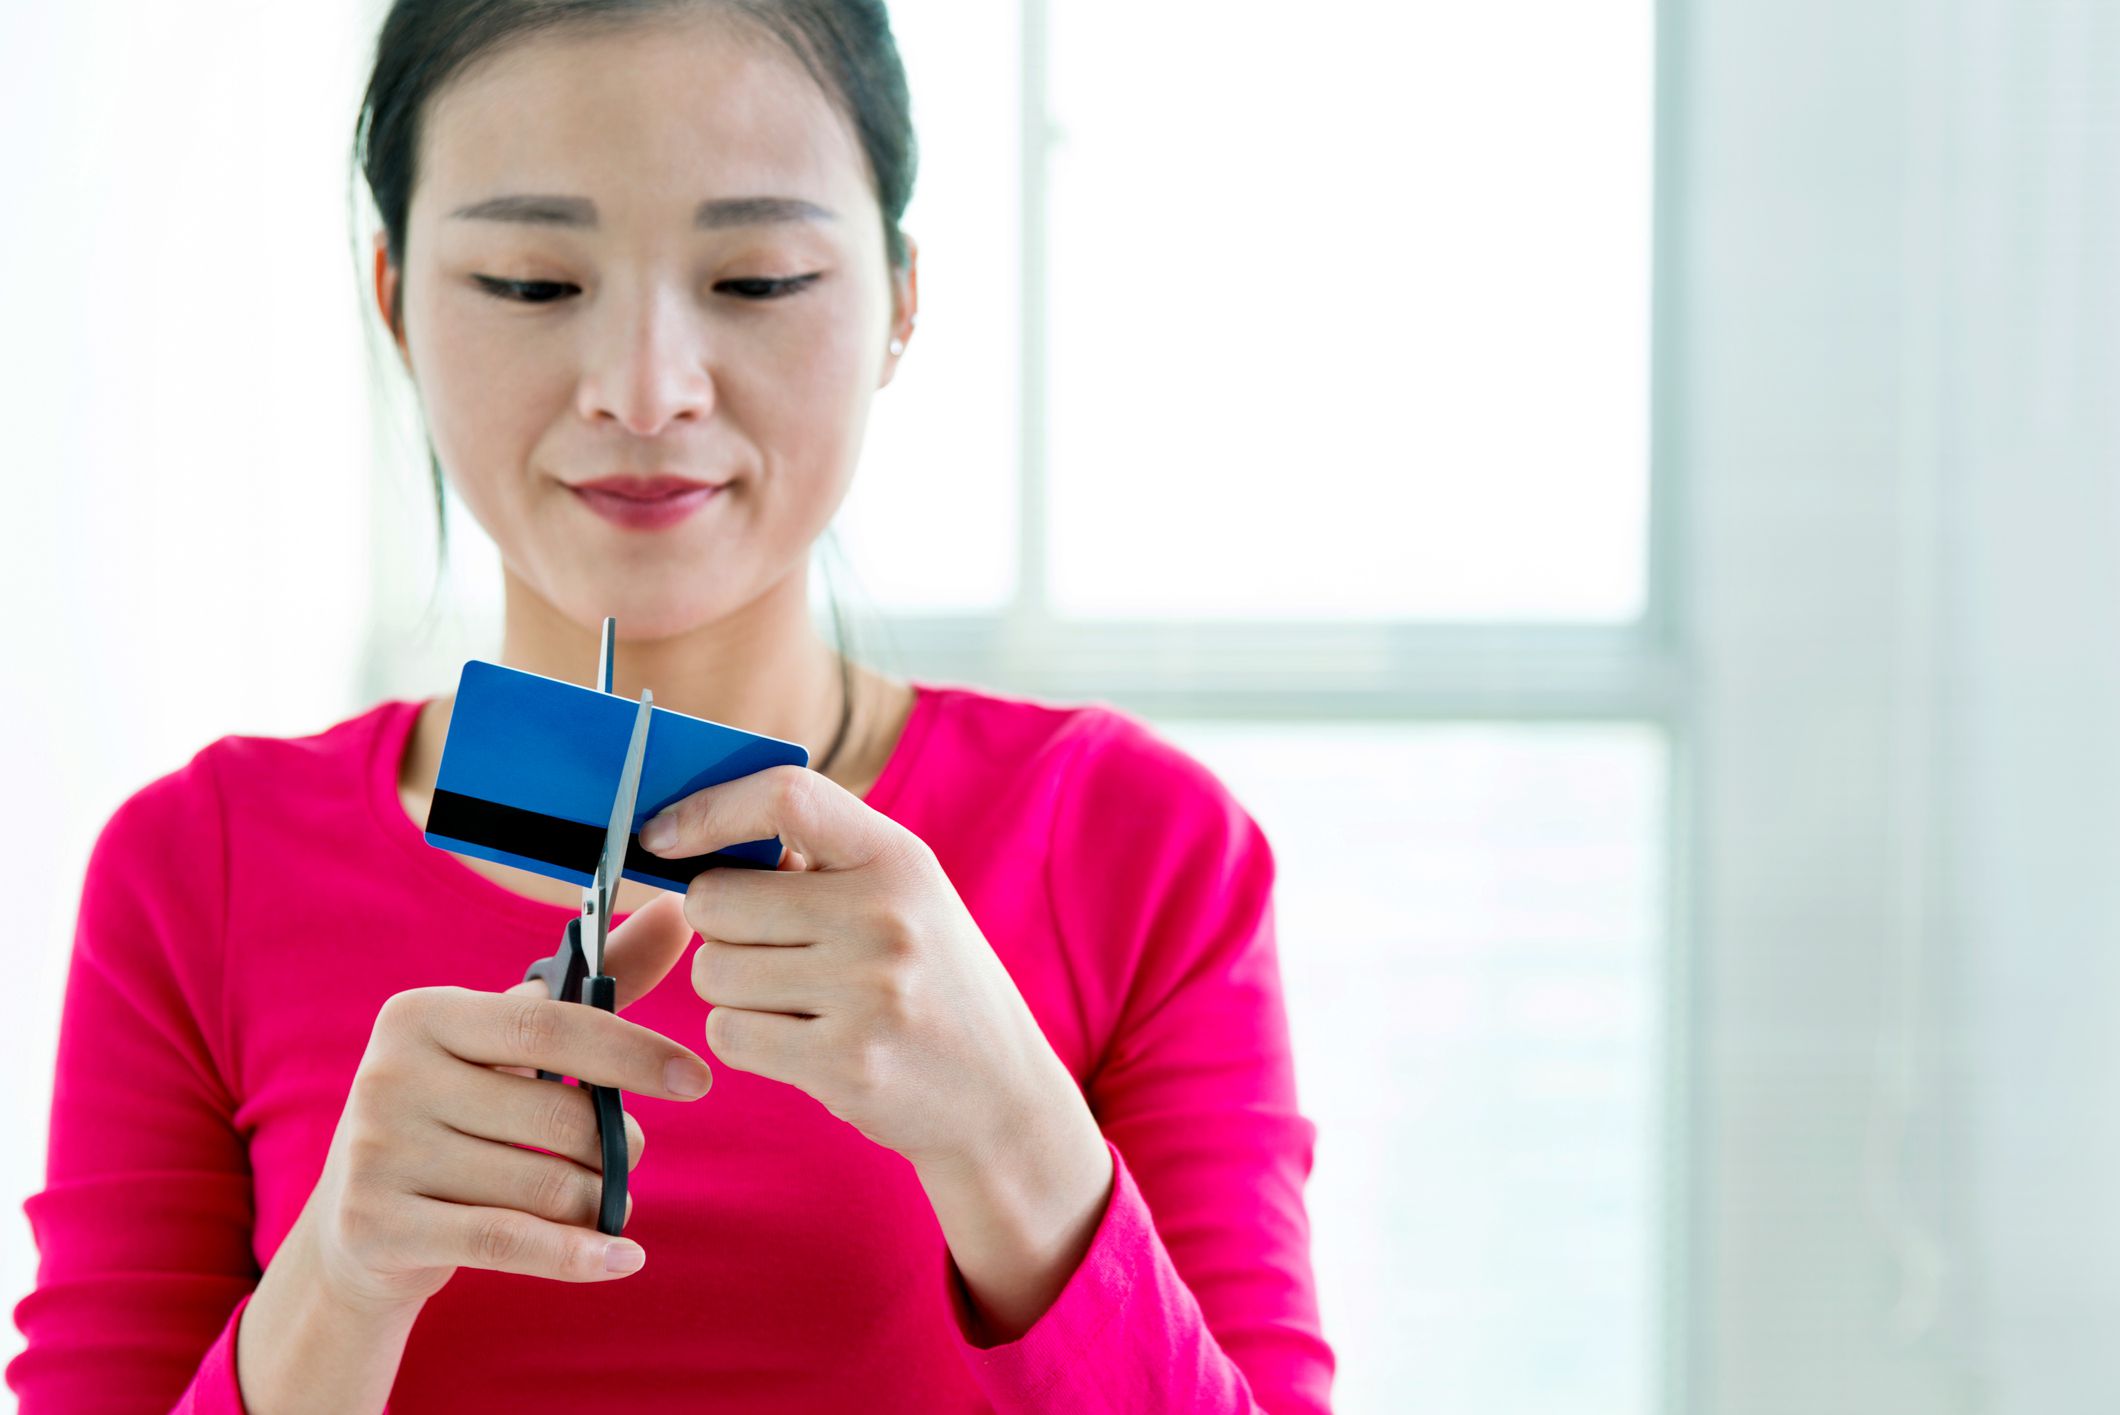
Other mistakes on this list can lead to even more borrowing, including having no emergency fund or failing to make sacrifices. Once you decide to pay down debt, do what you can to avoid taking on new balances. Some experts even recommend cutting up credit cards.
Forgetting to Budget
A budget is one of the most important tools for paying off debt. You cannot make meaningful progress if you do not know where your money is going. Reviewing your budget can also reveal spending patterns and show where you can cut back to focus more on debt repayment.
Mindless Spending
In the digital age, it is easy to buy almost anything instantly, often with free shipping. That convenience can become a major obstacle when you are trying to pay off debt. If you want something, wait at least 24 hours before buying it so you can decide whether you really need it.
Keeping the Same Habits
If you try to pay off debt without changing your spending habits, you are likely to be disappointed. As the saying goes, if you keep doing what you have always done, you will keep getting the same results.
Letting Hopelessness Take Over
After adding up your balances, it is easy to feel discouraged. The total may seem impossible to overcome. But giving in to hopelessness can keep you stuck. One of the biggest mistakes you can make is not believing you can succeed.
Not Tracking Your Progress
If you do not measure your progress, it may feel like you are getting nowhere. In reality, you may be making steady gains. Tracking your debt payoff helps you see movement and can make the process feel more rewarding. Printable trackers can help visualize your progress.
Failing to Celebrate Small Wins
Along the way, you will likely hit important milestones. Paying off a first credit card or finishing a car loan deserves recognition. Celebrating small victories can keep you motivated as you work toward the larger goal, and it does not have to cost anything.
More Cheapism Reads To Help You Defeat Debt
- What Affects Your Credit Score and Tips to Help Improve It — Learn how unpaid bills and reporting mistakes can hurt your credit, and what you can do to protect it.
- 21 Ways To Reduce Your Monthly Bills When Money Is Tight — Practical ideas for lowering monthly expenses and easing pressure on your budget.
- 50+ Things You Absolutely Never Need to Buy — A look at common purchases that can waste money and make debt harder to escape.
More from Digilifetrends
Beshear provides update on Medical Debt Relief Program
After the launch of the Team Kentucky Medical Debt Relief Program, Governor Andy Beshear said the effort has continued to make progress toward eliminating $250 million in medical…
1 min read · Published 2026-11-03Student Loan Transition Deadline Has Passed: What Borrowers Should Do Now
A key deadline has now passed for some borrowers who were enrolled in the discontinued Saving on a Valuable Education, or SAVE, repayment plan.
5 min read · Published 2026-11-02Judge says Trump’s student-loan borrowing cap for advanced degrees would cause immediate harm
A federal judge has delivered another setback to the Trump administration’s effort to cap student-loan borrowing.
2 min read · Published 2026-11-02