Americans carrying student loan debt are facing one of the biggest shifts in federal repayment programs in years, and the changes are unsettling for many borrowers.
One major development is the end of the popular SAVE repayment plan, which is forcing millions of borrowers into new plans that could bring heavier monthly payments as 2027 nears.
Here’s a look at what Intuit Credit Karma says is happening with student loans.
Key takeaways from the report
Credit Karma reviewed TransUnion data for 24.2 million members with open student loan debt at the end of the third quarter of 2026. These are the main findings from that analysis.
People are also reading…
1. Borrowers with loans in deferment — about 10.1 million Credit Karma members with student loans — appear especially vulnerable financially, since many may soon have to restart payments.
- 14.7% are behind on other debt, compared with 8.2% of borrowers who are fully current and actively repaying their loans
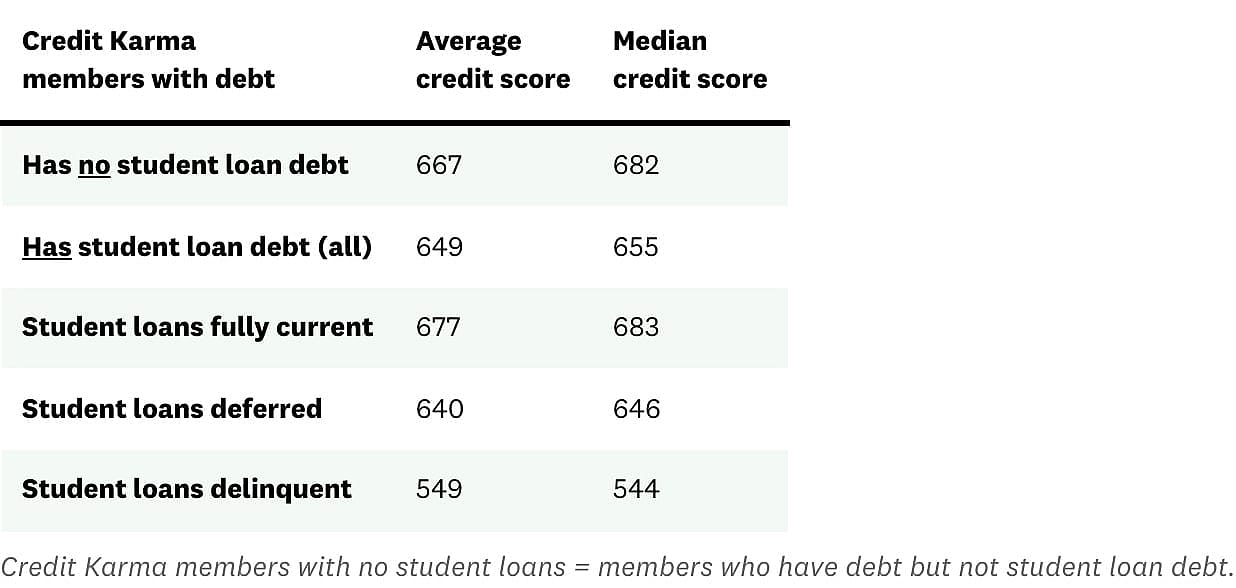
- The median credit score for the deferred group is 37 points lower than the fully current group’s (646 vs. 683)
2. Borrowers with the smallest student loan balances are the most likely to be delinquent.
- Borrowers with less than $10,000 in student debt — the lowest balance band — have the highest delinquency rate.
- This mirrors broader consumer debt trends, since many accounts that end up in collections are relatively small credit card, phone and utility balances.
3. Gen Z and millennials together account for nearly three-quarters of student loan borrowers, but Gen X is delinquent at a slightly higher rate than younger generations.
- Gen X student loan delinquency stands at 10.4% of members, versus 9.7% for millennials and 9.6% for Gen Z.
- Gen Z has the largest share of borrowers in deferment, which fits with where many are in life.
Credit Karma’s student loan population: 2026 snapshot
Credit Karma has 24.2 million members with open student loans totaling more than $1 trillion.
Roughly 95% of those loans are federal rather than private. For comparison, Federal Student Aid says there are about 42.3 million federal student loan borrowers nationwide.
To better understand this population, Credit Karma divides members into three groups based on student loan status.
Population segments
How many borrowers are current, deferred or delinquent?
As the final quarter of 2026 approached, more than 48% of Credit Karma members with student loans were fully current on all of their loans, while close to 10% were delinquent.
Another large share — more than 41% — had at least one student loan in deferment.
Borrowers with deferred loans are showing more signs of strain than those paying on all of their loans, including a lower median credit score and a higher share behind on other debt.
The smaller delinquent group is under the most pressure, with nearly a quarter struggling with other debts.
This breakdown matters because, as former SAVE borrowers move into new plans, a large portion of the deferred group could become fully current in the near term. Over time, the delinquent group could also grow.
It is not clear how many Credit Karma members were on SAVE, but the U.S. Department of Education estimated 7.5 million borrowers nationwide were enrolled in the plan.
Student loan data by generation
Younger generations generally have lower balances and a larger share in deferment. One likely reason is that they have had less time to build up student debt, and fewer have moved fully into repayment.
The table below shows the share of each generation that is fully current, deferred or delinquent, along with total and median balances and median credit scores.
Which generations are dealing with the most delinquency?
This table breaks down student loan delinquency by generation, including how many borrowers are delinquent and what share are 90 to 269 days past due or 270 days or more past due.
Severity of student loan delinquency by generation
Federal loan servicers usually do not report late accounts to the credit bureaus until they are 90 days past due. Once that happens, the late mark can remain on a credit report for up to seven years. At 270 days past due, a federal student loan enters default. If the loan remains unresolved for 360 days, the government may garnish wages or take other collection action, such as seizing a tax refund.
Typical Gen Z borrower with student loan debt
Gen Z accounts for about a quarter of Credit Karma members with student loans. They tend to carry smaller balances than millennials, Gen X or boomers, and they have the highest deferment rate of any generation, which is unsurprising given their stage of life.
The table below breaks down Credit Karma’s Gen Z members with open student loans by loan status and shows their average and typical credit scores, as well as the median balance per borrower.
The next table shows how Gen Z borrowers with student loans are handling other kinds of debt.
Consistent with the wider student loan population, the deferred group is more burdened by other debt, including personal loans and credit cards, than Gen Z borrowers with student loans overall.
Gen Z student loan borrowers behind on other debt
Typical millennial borrower with student loan debt
Millennials make up about half of Credit Karma members with student loans, and most are now in their 30s or early 40s.
The table below breaks down Credit Karma’s millennial members with open student loans by loan status and shows their average and typical credit scores, plus the median balance per borrower.
As with Gen Z and the broader student loan population, millennials whose loans are in deferment are more likely to fall behind on other debts than millennials with student loans overall.
Mortgage and auto payment delinquency stands out as a bigger issue for millennials than for their younger peers.
Millennial student loan borrowers behind on other debt
Debt loads and delinquency
The table below shows that the highest student loan delinquency rates are found in the two lowest debt bands.
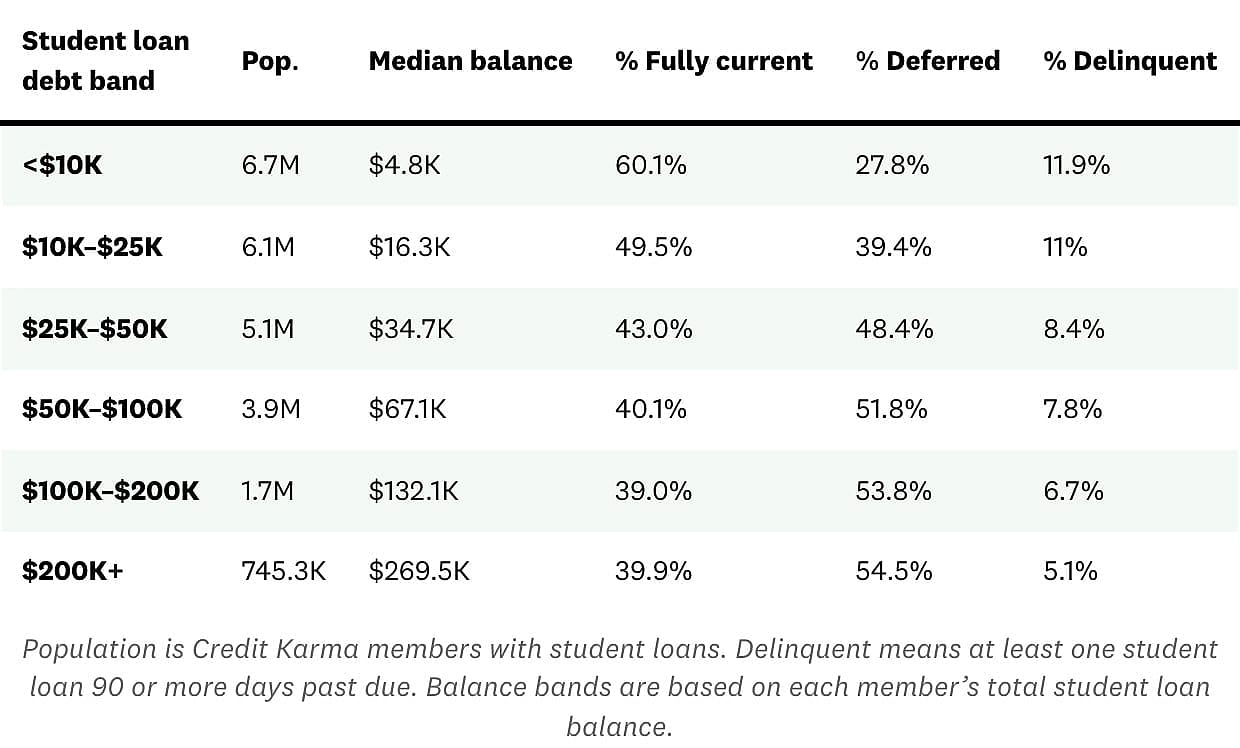
That may seem surprising, but a Brookings Institution study found that the smallest balances often belong to people who left school before finishing, and lower earnings were a major factor in their default rates. The broader point is that falling behind often has more to do with financial stability than with the amount owed.
Other consumer debts show a similar pattern: most accounts that end up in collections are small. In 2026, the typical non-medical debt in collections on Credit Karma members’ credit reports was under $700, largely from credit cards and basic bills such as utilities and phone service. Small unpaid bills can be a sign of a tight budget where even routine expenses are difficult to cover.
Student loan data: Credit cards and other debt
The table below compares how often borrowers in each student loan group fall behind on other debts, such as credit cards and loans, with members who do not have student loan debt.
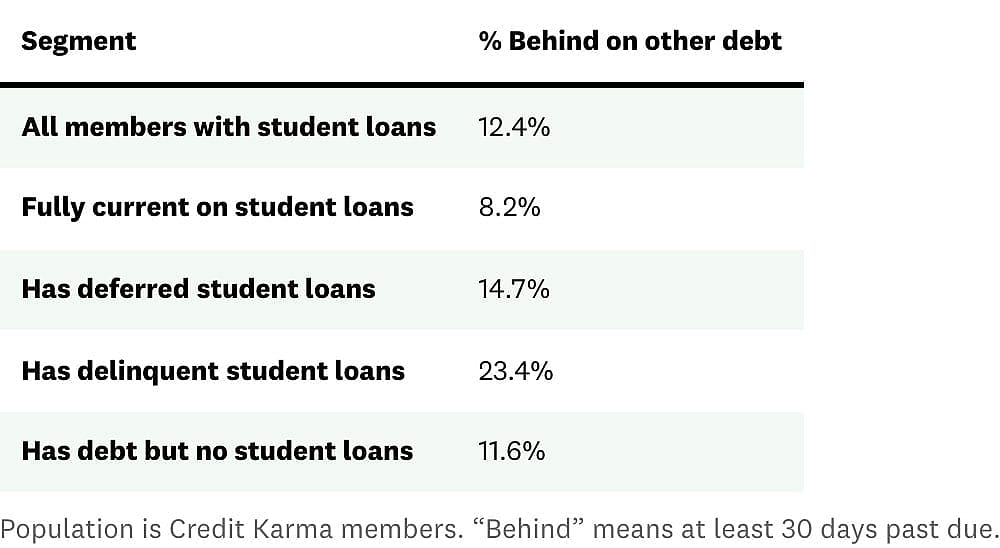
Even with student loans paused, the deferred group falls behind on other debt more often than members without student loan debt.
By contrast, the fully current group appears healthiest, even compared with people whose debt does not include student loans.
Student loan data: Credit scores
As a group, student loan borrowers have average and median credit scores that are noticeably lower than those of people whose debt does not include student loans.
But when the analysis looks only at borrowers who are fully current and actively repaying, the picture changes: that subgroup has a better average score than people without student loans, and a median score that is nearly the same.
Student loan data: Score bands
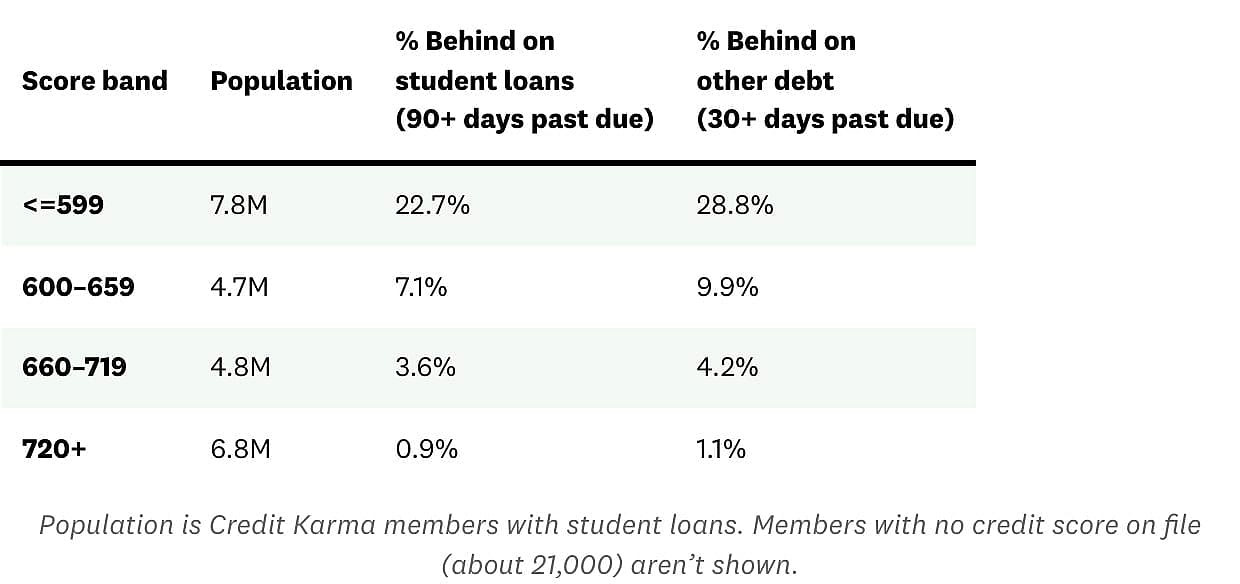
Score bands can only tell you so much about delinquency, because falling behind on an account also lowers a credit score.
Still, the table below offers clues about how much trouble lower-scoring student loan borrowers are having with other debts such as credit cards and loans, including personal, auto and home loans.
Methodology: Credit Karma student loan data
This report is based on TransUnion credit reports for 24.2 million Credit Karma members with open student loans as of Sept. 30, 2026. Credit Karma counts open accounts that TransUnion classifies as student loans, regardless of who reports them. Generations are defined by birth year: Gen Z (1997 and later), millennials (1981–1996), Gen X (1965–1980), baby boomers (1946–1964), and the Silent Generation and older (before 1946). Each member is placed into one of three groups — fully current, deferred or delinquent — based on the worst student loan in their file. Fully current means all loans are in active repayment and in good standing; deferred means at least one loan is in deferment or forbearance and none are reported past due, though current loans may also be present; delinquent means at least one loan is 90 or more days past due. Members whose worst student loan was reported 30 to 89 days past due, fewer than 1%, are not included in any group, so totals may not add to 100%. Credit scores are VantageScore 3.0 as of early October 2026, and members without a score are excluded from the score figures. Being “behind” on other debt means being at least 30 days past due. Members without student loan debt have at least one open credit account but no student loans. Collections figures cover non-medical accounts in collections on members’ TransUnion credit reports.
FAQs about student loan debt
What is the typical student loan debt?
Among Credit Karma’s 24.2 million members with student loans, the median total balance was about $23,000 as of September 2026. That is broadly in line with the Federal Reserve’s latest Survey of Consumer Finances, which found a median balance of about $24,500 among families with student debt in 2022.
How can delinquent student loans affect your credit score?
Loan servicers usually do not report late federal student loan payments until they are 90 days past due. Once they do, your credit scores can be hurt just as with other accounts. If you are concerned, review student loan resources or consider contacting the nonprofit TISLA for free advice.
How can I get forgiveness on a student loan?
One major federal route to student loan forgiveness is Public Service Loan Forgiveness, or PSLF, which may be available to people working full time for an eligible government agency or nonprofit. PSLF can forgive the remaining balance on federal Direct Loans after 120 qualifying monthly payments. You can check the details through Federal Student Aid’s forgiveness information.
What is the Standard Repayment Plan for federal student loans?
The Standard Repayment Plan divides your balance into fixed monthly payments for up to 10 years, or 10 to 30 years for consolidation loans. If you do not choose a repayment plan, your servicer will place you on this one. It usually means higher monthly payments, but less total interest over time. Federal Student Aid can help you compare repayment options.
What is the difference between a delinquent and a defaulted federal student loan?
A federal student loan is considered delinquent as soon as you miss a payment, but servicers usually do not report it as late to the credit bureaus until it is 90 days past due. After that, it can damage your credit. At 270 days past due, the loan goes into default, which can eventually lead to wage garnishment and tax refund seizure.
More from Digilifetrends
Debt snowball or debt avalanche? The right payoff strategy hinges on one factor
Best - stock.adobe.com
8 min read · Published 2026-10-29‘Operation Ghostbusters’ Uncovers ‘Ghost Student’ Loan Scam, Leads to Five Indictments
AP Photo/Wally Skalij
6 min read · Published 2026-10-29New lawsuit claims thousands of borrowers from closed schools were wrongly denied student-debt relief
The Education Department is facing another legal challenge over unpaid student-debt relief.
2 min read · Published 2026-10-29